Growth is an exciting milestone for any financial advisory practice. But as a client base expands, so does the complexity behind the scenes: more meetings, more administrative work, more coordination, and more decisions competing for an advisor’s attention.
At a certain point, working harder is no longer a sustainable growth strategy. The next step is learning how to run the practice like a business, not simply managing the next task on the calendar.
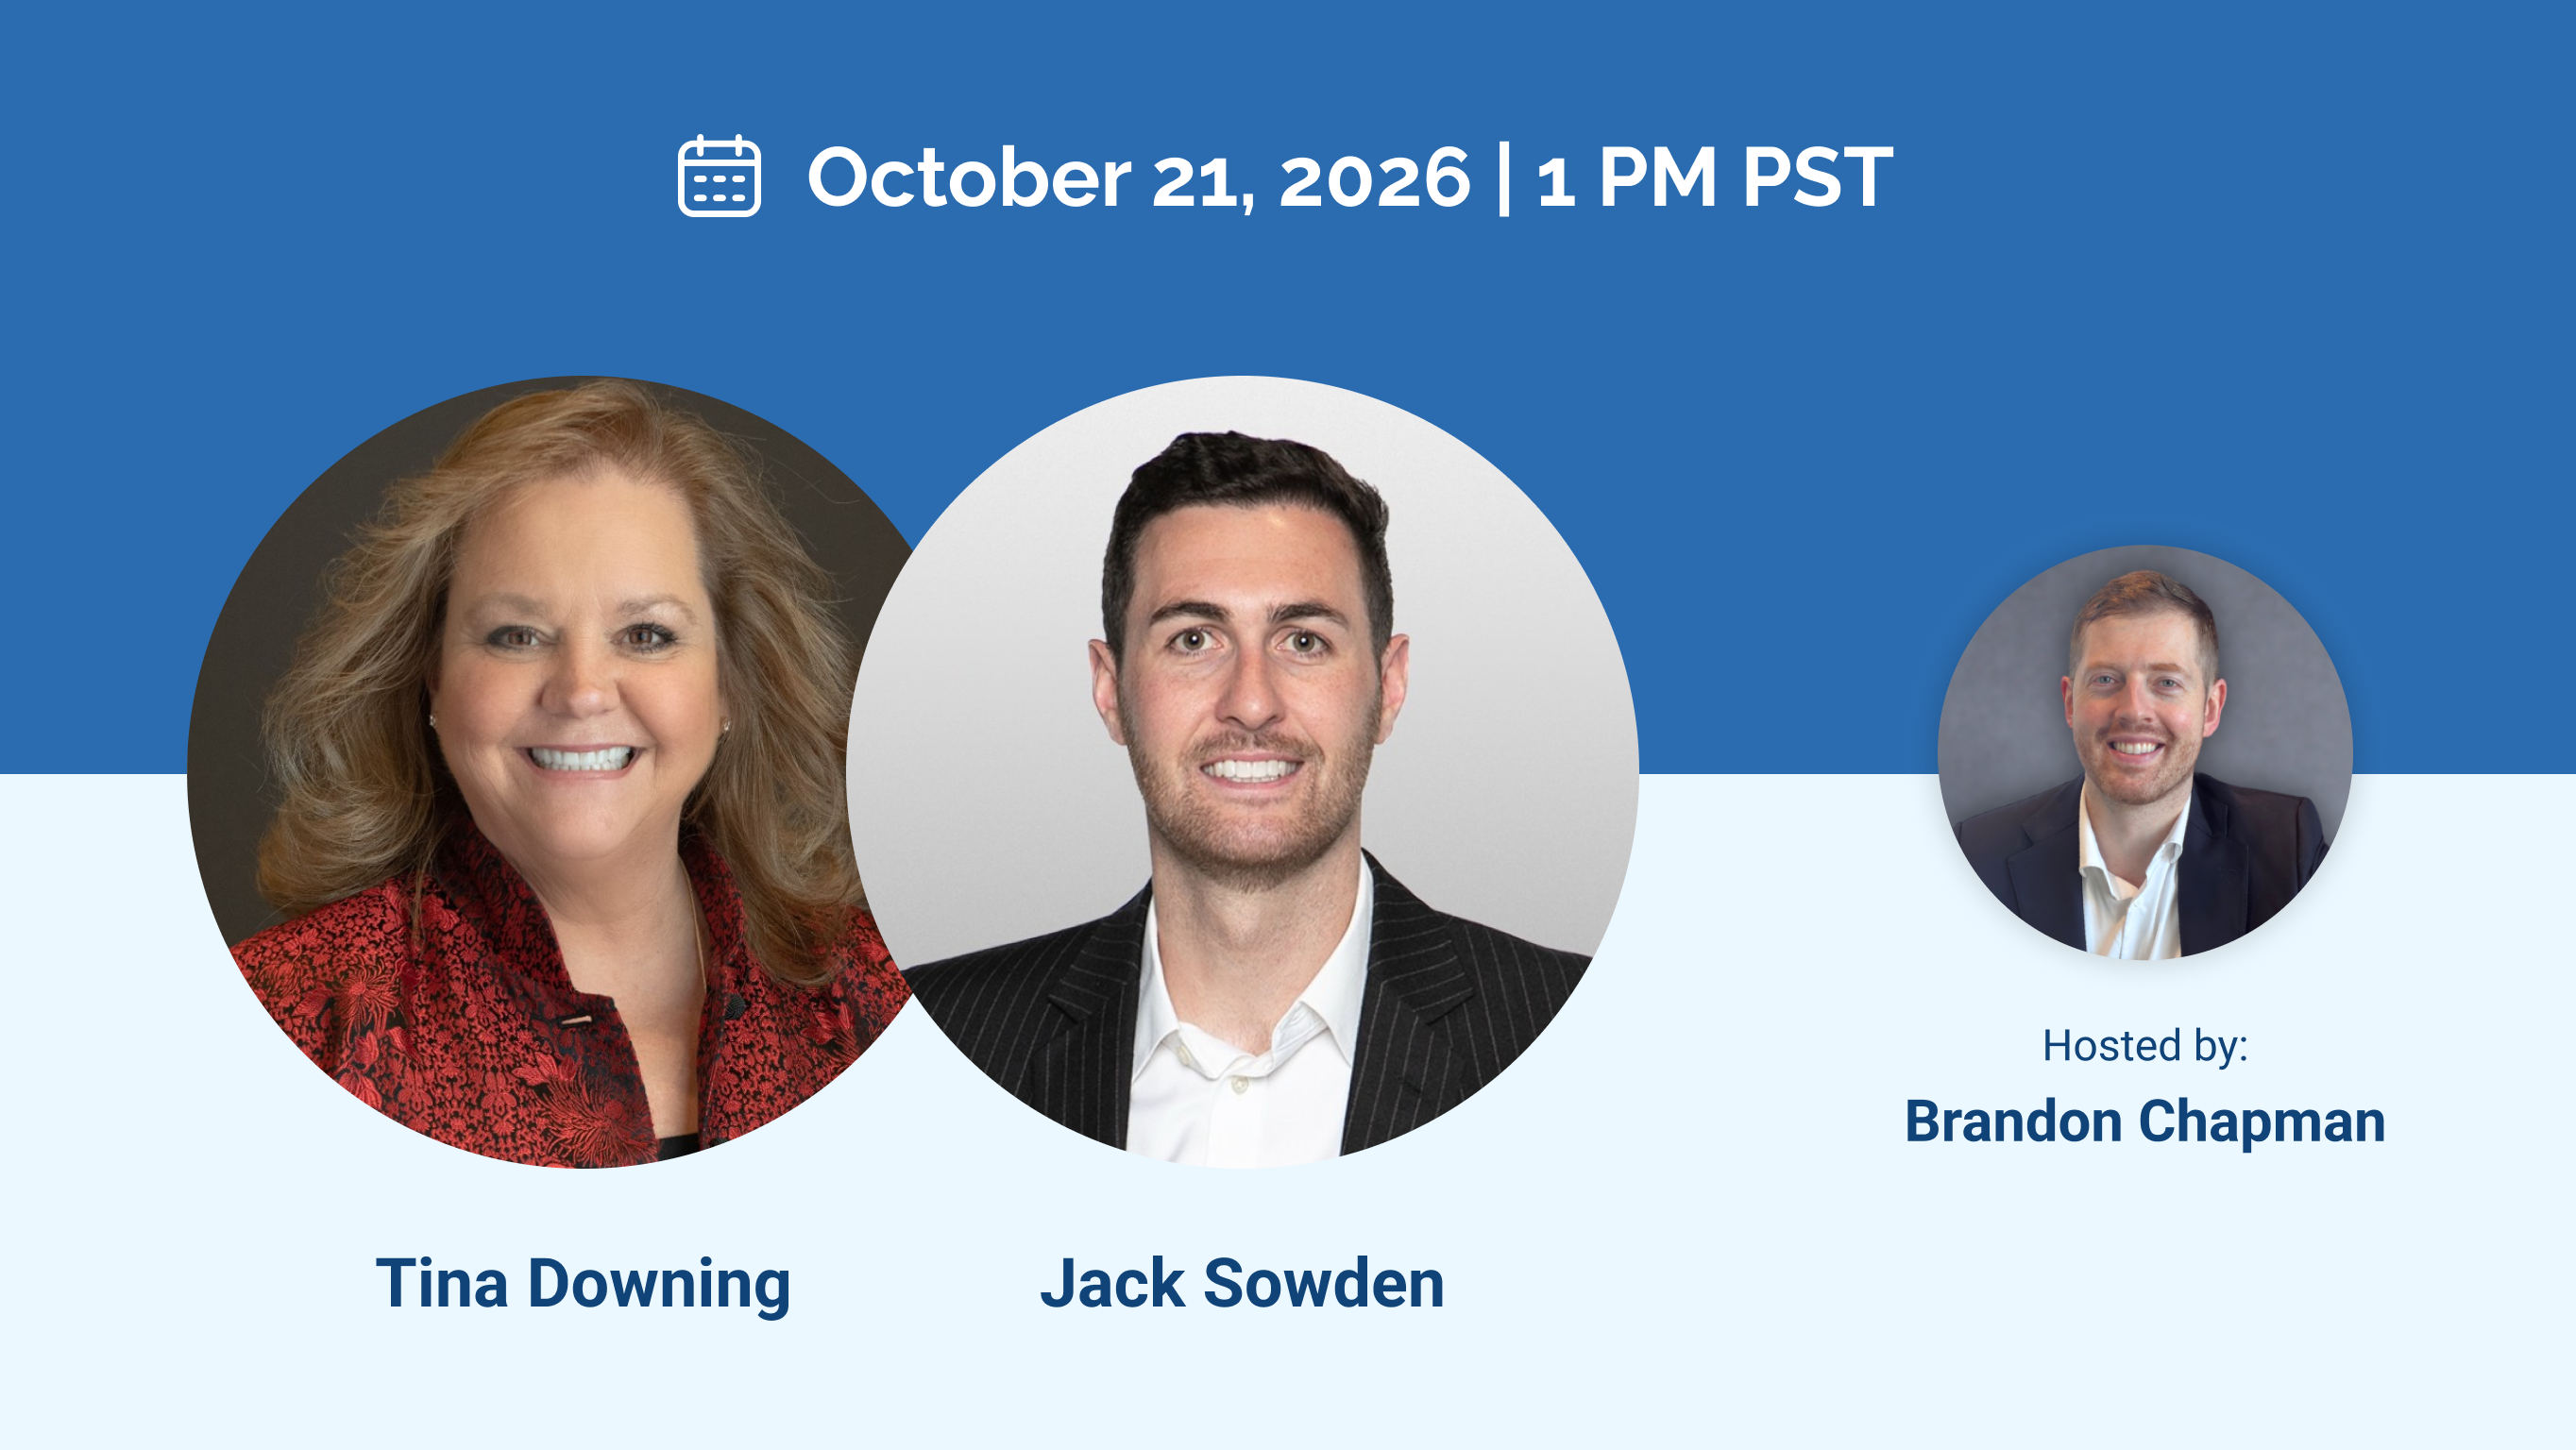
At AdvisorFlow’s hybrid event, “Run Your Practice Like a CEO: Strategy, Systems & Growth for 2027,” Brandon Chapman of AdvisorFlow joined Tina Downing and Jack Sowden of Russell Investments to explore how advisors can build a more intentional, scalable practice. The discussion covered strategic planning, team structure, client experience, time management, and the role of technology in reducing operational friction.
The central message was simple: sustainable growth requires more than a revenue target. It requires a clear vision, a plan to reach it, and the people and processes to put that plan into action.
Watch the full webinar:
Shift From Working in Your Practice to Leading It
A growing advisory practice can easily become reactive. Client requests, administrative work, staff questions, and operational issues take priority, leaving little time to think about the direction of the business.
A CEO mindset means stepping back from day-to-day responsibilities long enough to ask bigger questions:
- What do you want your practice to be known for?
- Which activities create the most value for your clients and your business?
- Are your systems supporting the client experience you promise?
- Does your team understand who owns each responsibility and decision?
- Could your practice continue operating effectively if you stepped away?
These questions help advisors distinguish between being busy and making meaningful progress.
Growth also needs to be sustainable. Taking on more clients without improving the systems and team structure behind the business can create operational drag. Over time, that complexity may affect responsiveness, consistency, and the quality of the client experience.
The goal is not to distance yourself from clients. It is to build a business that can serve them consistently without relying on one person to carry every decision, relationship, and task.
Use a Five-Part Framework to Guide Your Strategy
A useful way to approach practice management is to break it into five connected components: Vision, Analysis, Strategy, Structure, and Execution.
Each component serves a different purpose, and the framework works best when the pieces support one another.
Vision: Define what success looks like
Before deciding what to change, determine what you want to build. Consider what you want to be known for, whom you want to serve, and what you want your practice to look like in three, five, or ten years.
Your vision should be specific enough to guide decisions. Without it, new opportunities can become distractions rather than steps toward a clear destination.
Analysis: Understand where you are today
Review the current state of your business before committing to a new initiative. This may include referrals, new-client conversion, prospecting activity, client relationships, workload, profitability, and the sustainability of your production.
Understanding your starting point helps you identify where the greatest opportunities and constraints exist. It also makes it easier to evaluate whether a proposed change is likely to move the business forward.
Strategy: Decide what needs to change
With a clearer picture of your current position and future goals, identify the priorities that matter most.
Ask what is working, what is not, what threats could affect the practice, and what needs to change over the next year. A revenue target is an outcome to pursue, but it is not a strategy by itself. The strategy is the set of decisions and actions that can help you reach that outcome.
Structure: Give people clear responsibilities
Even a strong strategy can stall if responsibilities are unclear. Determine who owns key outcomes, such as prospecting, marketing, existing-client relationships, and operational follow-through.
Rather than assigning work without considering capacity, first identify what needs to be done and where the gaps are. Then determine the roles, resources, and support needed to fill them.
Execution: Turn decisions into action
Finally, translate priorities into specific commitments. For each initiative, establish what will happen, who is responsible, and when it needs to be completed.
Execution also means deciding what to stop doing. Adding new projects without removing lower-priority work can increase workload without creating meaningful progress.
A written strategy becomes valuable when it changes how the team spends its time, makes decisions, and serves clients.
Build a Client Experience That Sets Your Practice Apart
A strong client experience is more than providing good advice. It is the combination of your service model, communication, processes, and the consistency clients experience throughout the relationship.
During the webinar, the speakers introduced the RAVE test as a way to think about how a practice differentiates itself:
- Rare: What do you offer that is genuinely distinctive?
- Advocacy: How are you building relationships that encourage clients to recommend you?
- Value: Do you understand what your clients actually value?
- Experience: Is the experience you deliver difficult for competitors to imitate?
These questions can help advisors evaluate potential initiatives before investing time and resources in them.
For example, adding another service or communication channel may sound appealing. But will it make the experience more valuable to the clients you want to serve? Will it strengthen relationships or simply add another process for the team to manage?
The same thinking applies to product strategy. A wider product offering can introduce additional complexity through education, monitoring, communication, compliance, reporting, and ongoing service. Advisors should periodically assess whether their offerings still support their target clients and the type of practice they want to build.
A deliberate approach can help teams focus on the solutions they understand well and deliver consistently.
Turn Your Business Plan Into a Working Document
A business plan should be more than a document created at the beginning of the year and revisited when it is time to set new targets.
It should be a living reference that helps the team understand its priorities, measure progress, and make adjustments as circumstances change.
A useful plan can include:
- Values and vision: What does the practice stand for, and whom does it aim to serve?
- Differentiators: What makes the practice valuable to its target clients?
- Success measures: Which revenue, activity, retention, or referral metrics will indicate progress?
- Priorities: What are the most important changes to make over the coming year?
- Accountability: Who owns each action, and when will progress be reviewed?
Tools such as SMART goals: Specific, Measurable, Attainable, Relevant, and Timely, can help translate broad ambitions into concrete actions. A SWOT analysis can also help teams examine strengths, weaknesses, opportunities, and threats.
Regular reviews are just as important as setting goals. Compare actual progress against expectations, identify what has changed, and decide what to do next. The purpose is not to maximize every metric or abandon an initiative as soon as results take time. It is to learn, adapt, and remain focused on the outcomes that matter.
Most importantly, planning should involve the people responsible for carrying it out. A plan is more likely to influence daily work when the team understands the priorities and has a role in shaping them.
Protect Your Time and Build Team Capacity
Time management is also a business strategy. How an advisor spends the working week should reflect the priorities they say matter most.
One practical starting point is to review the calendar over several weeks and categorize the work being done. This might include client advice and relationship management, business development, team leadership, administration, and rework or interruptions.
The exercise can reveal a gap between the work that drives the business forward and the work that fills the day.
Advisors can then look for opportunities to protect time for important but non-urgent activities, such as strategic planning, relationship development, and team leadership. These activities are easy to postpone because they rarely demand immediate attention, but consistently neglecting them can limit future progress.
Capacity is not only about personal productivity. It also depends on whether the team understands its responsibilities, has the resources to perform them, and can move work forward without unnecessary bottlenecks.
When assessing team structure, consider what would happen if the lead advisor were suddenly unavailable. Are client relationships, key responsibilities, and important knowledge shared appropriately? Is there a clear continuity or succession plan?
Succession planning is not simply a document or a future ownership decision. It also involves preparing people, transferring knowledge, and ensuring clients continue to receive consistent service through a transition.
Use Technology to Support a Better Process
Technology can help advisory practices reduce manual work, improve consistency, and create more capacity. But buying another tool is not necessarily the first step.
Start by identifying the outcome you want to improve. Where does information get entered more than once? Which tasks depend entirely on the advisor? Where are handoffs unclear? Which parts of the client journey create unnecessary delays?
Once the process is understood, determine how technology can support it. Sometimes the best solution is a new integration. In other cases, it may be making better use of an existing tool, reducing handoffs, or improving the way information is organized.
A practical example: Systemizing an advisory practice
Brandon shared lessons from operating SaaS Wealth Insurance alongside AdvisorFlow. As the practice grew, maintaining consistency required more than adding capacity. The team needed clearer processes and ownership.
The approach included several steps:
- Document repeatable work. Standard operating procedures help clarify how recurring tasks should be completed, who owns each step, and when an issue should be escalated.
- Assign responsibilities. Different team members take ownership of defined parts of the client journey, from advice and planning to administrative follow-through.
- Standardize information gathering. Structured forms can help collect information at key stages, such as discovery, financial reviews, insurance needs, and client updates.
- Reduce unnecessary handoffs and re-entry. Connecting workflows and systems can help the team use client information more consistently instead of repeatedly searching for or entering the same details.
- Use AI with appropriate oversight. AI can assist with tasks such as brainstorming, drafting, and preparing market summaries, but people must still review outputs, verify information, and remain accountable for decisions.
The important lesson is that a scalable system is not just a collection of software. It combines a documented process, clear ownership, a consistent client experience, and tools that support the way the team works.
AI should be approached in the same way. It can support human expertise, but it does not replace professional judgment, accountability, or the need to protect sensitive information.
Choose One Change to Start With
A more scalable practice does not have to be built all at once. The most useful next step may be a small, clearly owned change that addresses a recurring source of friction.
To put the webinar’s framework into practice, consider five questions:
- Vision: What is one thing you want your practice to be known for?
- Analysis: What is one metric you will track consistently?
- Strategy: What is one change that would move the business closer to its goals?
- Structure: Who needs to own the outcome?
- Execution: What will you start, and when?
The answer might be a calendar audit, a clearer service model for different client segments, a more consistent new-client follow-up process, or documenting one repetitive workflow.
Choose an action that is manageable, assign an owner, set a date, and schedule a time to review the result. Small improvements become more valuable when they are implemented consistently and built into the way the practice operates.
Running a practice like a CEO is not about spending less time with clients. It is about making deliberate decisions about the business behind those relationships, s,o the team can deliver a consistent experience while creating room for sustainable growth.
How AdvisorFlow Can Help
Technology is most effective when it supports a well-defined process. For growing advisory teams, reviewing the current workflow can help identify where manual data entry, disconnected systems, and unclear handoffs are creating unnecessary work.
AdvisorFlow helps financial advisors collect client information through digital forms and workflows, organize document exchange, and connect information with the tools they use to manage their practices.
If you are looking to improve your onboarding process or create more capacity as your practice grows, contact AdvisorFlow to explore a complimentary technology review. Together, you can identify workflow friction and consider practical next steps for building a more connected practice.


